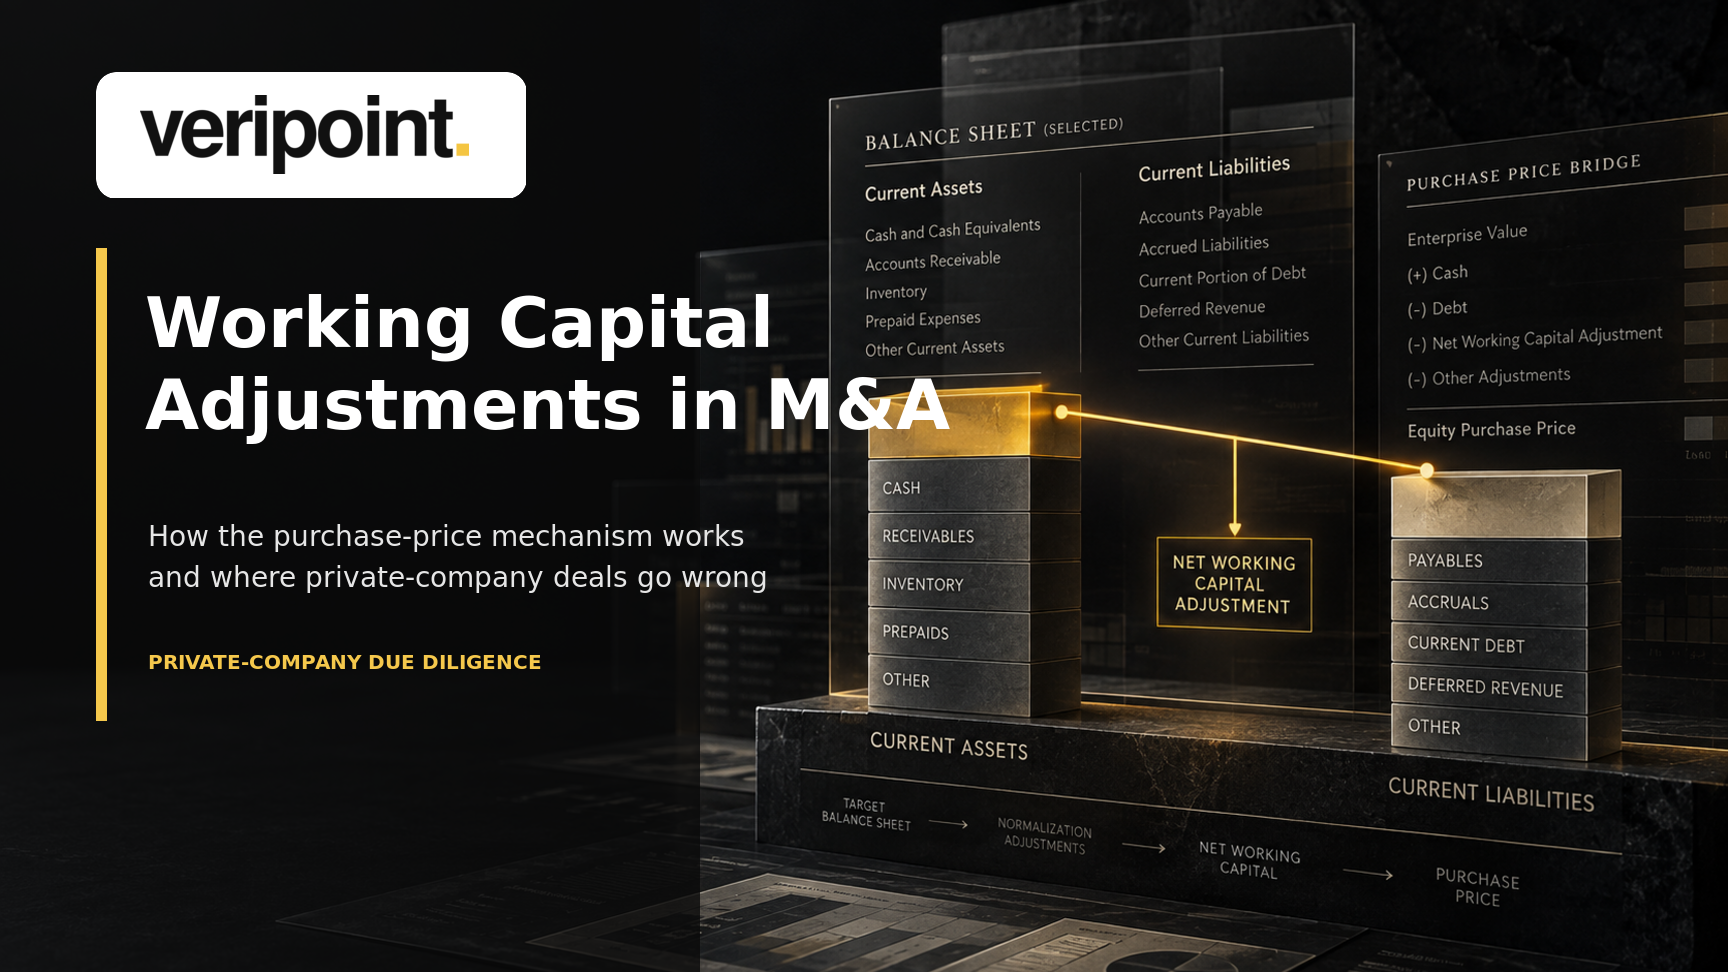
Buying a company at an agreed enterprise value does not mean the seller receives that number. The final equity purchase price usually moves for cash, debt and the level of working capital delivered at completion. A working capital adjustment ensures the buyer receives a business with a normal amount of operating liquidity—not one temporarily stripped of cash-generating assets or loaded with unpaid operating liabilities.
The mechanism looks simple: compare closing net working capital with an agreed target, often called the working capital peg, then adjust the price by the difference. The difficult work sits inside the definitions. Which balances count? Which accounting policies apply? What period represents “normal”? How should seasonality, growth, old receivables, inventory provisions or deferred revenue be treated?
Those choices can move the price by far more than the parties expect. They can also create double counting if an item appears in both net debt and working capital. This guide explains the mechanism from a buyer’s and seller’s perspective, using illustrative private-company data throughout.
Five controls prevent most errors.
Define every included account before setting the target.
Calculate the historical series and closing statement on the same basis.
Adjust the peg for seasonality, growth and non-representative periods.
Keep working-capital and net-debt items mutually exclusive.
Test the mechanism with a real trial balance before signing.
What is a working capital adjustment in M&A?
A working capital adjustment is a post-signing or post-completion change to the purchase price based on the difference between the target company’s actual net working capital at closing and an agreed normal level.
The commercial logic is straightforward. An enterprise-value offer normally assumes the company will be delivered cash-free, debt-free and with enough working capital to continue operating in the ordinary course. If the seller delivers less than the agreed working capital target, the price usually falls dollar for dollar. If the seller delivers more, the price usually rises dollar for dollar.
A positive result increases the equity purchase price. A negative result reduces it. The acquisition agreement controls the exact sign convention, currency, rounding, thresholds and dispute process.
This is not the same as asking whether accounting working capital is positive. A retailer or subscription business can operate normally with negative working capital because customers pay before suppliers are due. The target should reflect the normal operating level for that specific business under the definitions agreed for the transaction.
Net working capital and adjusted net working capital
In general financial analysis, net working capital is current assets minus current liabilities. In an acquisition, adjusted net working capital is narrower. It normally includes operating balances and excludes items already captured elsewhere in the price bridge.
A typical transaction definition starts with trade accounts receivable, inventory, prepayments and other operating current assets, then deducts trade accounts payable, accrued operating expenses and selected other operating current liabilities.
Cash, borrowings, accrued interest, shareholder financing, transaction bonuses, sale costs, corporation tax and balances connected with discontinued operations are commonly excluded or treated elsewhere. There is no universal schedule. Deferred revenue, payroll accruals, VAT, customer deposits, factoring balances, capital-expenditure creditors and provisions regularly become negotiation points. The governing documents should contain an account-by-account definition and a hierarchy of accounting policies, not only a high-level formula.
How the purchase-price adjustment works
Assume a buyer agrees an enterprise value of $50.0 million for a private company. At completion, the company has $8.0 million of net debt. The agreed working capital peg is $5.2 million, but closing adjusted net working capital is $4.5 million.
The $0.7 million reduction does not mean the business is necessarily unhealthy. It means the buyer received $0.7 million less operating working capital than the level embedded in the deal assumptions. The buyer may need to fund that gap immediately after closing.
A $0.7m working-capital shortfall reduces equity value dollar for dollar.
How to set the working capital peg
The working capital peg is the benchmark against which closing working capital is measured. A twelve-month average is common because it can capture seasonality, but it should not be applied mechanically.
Start with at least twelve monthly balance sheets; twenty-four or thirty-six months are better for a seasonal or volatile company. Calculate adjusted net working capital consistently for each month using the proposed transaction definition. Then investigate the movements rather than simply accepting the mean.
Five questions the historical series must answer
- Is the reference period representative? A year containing a supply shock, acquisition, restructuring or unusually weak trading may not show the amount required for normal operations.
- Is the business growing? A fast-growing company may need more receivables and inventory at closing than its historical average. A backward-looking peg can understate the funding needed after completion.
- Is there seasonality? A year-end close for a holiday retailer should not be benchmarked against an unweighted annual average without understanding the operating cycle.
- Were balances managed around reporting dates? Delayed supplier payments, accelerated collections or inventory reductions can make a month-end figure look stronger than the underlying run rate.
- Are accounting policies consistent? Changes in cut-off, provisioning, capitalisation or account mapping can create apparent movements that are not commercial movements.
An annual average can hide the funding needed at the closing date.
The right target is not automatically the highest, lowest or average point. It is the amount that represents ordinary-course operation at the expected completion date under the agreed accounting rules. If closing occurs immediately before a seasonal build, the parties may agree a target below the annual average. If it occurs at the peak, the buyer may require more.
Build the definition before arguing about the number
Many working capital disputes are definition disputes disguised as valuation disputes. A strong schedule specifies whether each balance is included, excluded or treated as debt-like. It should also state whether balances are gross or net of allowances, how foreign currency is translated, how intercompany accounts are treated, and which chart-of-accounts codes map into each line.
| Balance | Typical treatment | Main diligence question |
|---|---|---|
| Trade receivables | Usually included | Are old, disputed or uncollectible balances adequately reserved? |
| Inventory | Usually included | Are slow-moving, obsolete or consignment items identified? |
| Prepayments | Included when operating | Will the buyer receive the future economic benefit? |
| Trade payables | Usually included | Have invoices been held back or suppliers paid unusually slowly? |
| Operating accruals | Usually included | Are payroll, bonus, warranty and service obligations complete? |
| Deferred revenue | Deal-specific | Does the buyer inherit delivery cost without the related cash? |
| Cash | Usually excluded | Is restricted or trapped cash genuinely available? |
| Short-term debt | Usually net debt | Would including it in working capital count it twice? |
| Transaction costs | Seller item or debt-like | Does the liability arise from the sale rather than operations? |
| Corporation tax | Often treated separately | Which party owns the pre-closing tax exposure? |
Accounting hierarchy: the clause that decides the dispute
The acquisition agreement normally includes an accounting hierarchy. A common order is: specific accounting principles written into the agreement; the agreed illustrative completion statement; accounting policies applied consistently in the reference accounts; and finally the applicable accounting framework.
The order matters. “In accordance with GAAP” or “in accordance with IFRS” is usually too broad on its own. Both can permit judgement, and a technically acceptable policy may still be inconsistent with the basis used to set the peg.
If the seller’s historical accounts reserve doubtful receivables after 120 days, the closing calculation should not silently move to 180 days. If inventory provisions were understated in the historical period, however, consistency alone may preserve an error. The parties need to decide during diligence whether to correct the historical series, adjust the peg or write a specific closing policy.
The most common working capital disputes
1. Receivables cut-off and collectability
Revenue recorded immediately before closing can increase receivables and closing working capital. The buyer should test whether the revenue was earned, whether credit notes followed, and whether the balance was collected. Old receivables require an allowance policy that matches the peg calculation.
2. Inventory quantity and valuation
Inventory may be counted but not saleable. Review ageing, write-downs, stock-count procedures, standard-cost variances, goods in transit, customer-owned goods and consignment stock. A high closing quantity should not increase the price if it contains obsolete items.
3. Delayed payments
A seller can preserve cash by delaying payments to suppliers, but the unpaid balance should increase payables and reduce working capital. Search for invoices received after closing that relate to the pre-closing period, unusual changes in days payable and suppliers placed on hold.
4. Accrued expenses
Management accounts may omit expenses that are recorded only at year-end. Bonuses, commissions, holiday pay, rebates, warranty claims, utilities and professional fees can create a closing shortfall if the accrual process is incomplete.
5. Deferred revenue and customer deposits
Deferred revenue is contentious because the seller may have collected the cash while the buyer must deliver the product or service. Some transactions include the full liability in working capital; others use the expected cost to fulfil or treat part of it as debt-like. The answer should follow the economics and avoid double counting.
6. Cash-like and debt-like items
Bank overdrafts, factoring, supply-chain finance, unpaid capital expenditure, leases, tax liabilities and related-party balances can fall between net debt and working capital. Every disputed line should appear in one place only. A complete price bridge should reconcile working capital, net debt and other purchase-price adjustments together.
Working capital sensitivity: why a small definition change matters
With closing adjusted net working capital fixed at $4.5 million and equity value before the adjustment at $42.0 million, every $0.1 million added to the peg reduces the final equity price by $0.1 million.
Every $0.1m added to the peg removes $0.1m from the final equity price.
| Working-capital peg | Adjustment | Final equity price |
|---|---|---|
| $4.8m | ($0.3m) | $41.7m |
| $5.0m | ($0.5m) | $41.5m |
| $5.2m | ($0.7m) | $41.3m |
| $5.4m | ($0.9m) | $41.1m |
| $5.6m | ($1.1m) | $40.9m |
| $5.8m | ($1.3m) | $40.7m |
This direct relationship explains why a debate about one reserve, accrual or excluded account can become a material price negotiation. The remedy is not a more complicated model. It is a clear definition supported by account-level evidence.
A practical working capital due diligence process
1. Confirm the legal entity and transaction perimeter
Map the company, subsidiaries, acquisitions and disposals. Ensure the monthly balance sheets, revenue data, debt schedule and purchase agreement cover the same entities. A group-level peg cannot be reconciled to a single-entity closing statement without a bridge.
2. Rebuild adjusted working capital monthly
Obtain monthly trial balances and map every account to included working capital, net debt, another adjustment or excluded. Recalculate at least twelve months using one consistent definition. Do not rely solely on summary management schedules.
3. Test the commercial drivers
Calculate receivable days, inventory days and payable days. Explain changes using sales mix, customer terms, supplier terms, purchasing patterns and seasonality. Ratios are diagnostic signals; they do not replace account-level testing.
4. Normalise unusual periods
Identify shutdowns, stock builds, exceptional contracts, acquisitions, supply disruption, rapid growth or deliberate balance-sheet management. Show the reported series and each proposed normalisation separately. Do not bury judgement inside a single adjusted line.
5. Reconcile the peg to the closing methodology
Use identical account mappings, provisions, currency treatment and accounting policies on both sides of the comparison. If the historical series and closing statement are prepared differently, the price adjustment measures accounting inconsistency rather than working capital delivery.
6. Run the dispute before signing
Prepare an illustrative completion statement using a recent month. Ask both advisers to calculate the result independently. Resolve ambiguous balances, access rights, deadlines, expert determination and materiality thresholds before the real closing calculation is due.
What public and private-company data can contribute
Filed financial statements can establish the legal entity, reporting dates, balance-sheet structure and multi-year movement in receivables, inventory, payables and other current balances where disclosure is available. Ownership data helps confirm the group perimeter. Filing history can reveal whether the latest accounts are current enough to support an initial view.
Veripoint can retrieve available private-company financials, compare reporting periods through financial statement analysis, and establish the company and group context before the data room is complete. The financial due diligence workflow helps turn that reported record into a structured question list.
Public records do not replace the closing calculation. Setting a defensible peg normally requires monthly management accounts, a trial balance, aged receivables and payables, inventory reports, accounting policies and transaction documents. Use external data to establish the baseline and identify gaps; use confidential records to test the actual mechanism.
Red flags before signing
- The peg is based on one balance-sheet date rather than a representative monthly series.
- The proposed definition says “current assets less current liabilities” without an account schedule.
- The company’s growth or seasonality is not reflected in the target.
- Receivables, inventory or payables spike in the weeks before closing.
- Historical provisions are reversed or accounting estimates change at completion.
- Deferred revenue is included without considering the cost to fulfil.
- The same liability appears in working capital and net debt.
- The reference accounts and closing statement use different entity perimeters.
- The agreement relies on an accounting framework but lacks transaction-specific policies.
- The illustrative completion statement has never been calculated using real trial-balance data.
The agreement is not finished if two people calculate two answers.
A working capital adjustment protects the operating level of short-term capital assumed in the deal. The best mechanism is one that both parties can calculate from the same ledger, using the same definitions, before completion.
Working capital adjustment questions, answered
Direct answers to the questions buyers, sellers and advisers ask when negotiating the purchase-price mechanism.
01What is net working capital?
Net working capital is current assets minus current liabilities. In M&A, adjusted net working capital normally includes only operating balances such as receivables, inventory, prepayments, payables and accruals. Cash, debt and transaction-specific liabilities are commonly excluded because they are addressed elsewhere in the purchase-price bridge.
02What is a working capital adjustment?
A working capital adjustment changes the purchase price by comparing closing adjusted net working capital with an agreed target or peg. If closing working capital is below the peg, the equity price generally falls dollar for dollar. If it is above the peg, the price generally rises, subject to the acquisition agreement.
03How do you calculate a working capital adjustment?
Subtract target net working capital from closing net working capital. If closing working capital is $4.5 million and the target is $5.2 million, the adjustment is negative $0.7 million. The agreement determines the included accounts, accounting policies, currency, rounding and sign convention.
04What is a working capital peg?
A working capital peg is the agreed normal level of adjusted net working capital the seller must deliver at closing. It is often informed by a twelve-month monthly average, then adjusted for seasonality, growth, acquisitions, unusual trading periods and the accounting definition used in the transaction.
05Does net working capital include cash?
Accounting net working capital can include cash within current assets. Transaction adjusted net working capital usually excludes cash because most enterprise-value deals use a cash-free, debt-free price bridge. Restricted cash or operational cash requirements need explicit treatment in the agreement.
06Is short-term debt included in working capital?
Short-term borrowings are usually treated as net debt rather than working capital. Including the same borrowing in both calculations would reduce the price twice. Overdrafts, factoring and supply-chain finance require specific classification because their accounting presentation may not reflect their transaction economics.
07Is deferred revenue included in net working capital?
It depends on the business and agreement. The buyer may inherit a future service obligation while the seller retains cash already collected. Transactions may include the full deferred-revenue balance, only the expected cost to fulfil, or treat part separately. Consistency with the peg and avoidance of double counting are essential.
08How is the target working capital calculated?
Calculate adjusted net working capital monthly over a representative period using the proposed deal definition. Review the average, median, seasonal pattern and operating drivers, then normalize unusual months and consider expected trading at closing. The target should reflect ordinary-course funding needs, not simply a formulaic average.
09How does a working capital adjustment affect the purchase price?
The adjustment normally changes equity value dollar for dollar. A $0.8 million shortfall against the peg usually reduces the price by $0.8 million; an equivalent surplus increases it. Thresholds, collars, caps or one-way mechanisms may change that result if written into the agreement.
10What is the difference between a working capital adjustment and a locked-box deal?
Completion-accounts deals calculate cash, debt and working capital at closing, then adjust the price after the event. A locked-box deal fixes the equity price using an earlier balance sheet and protects value through leakage provisions. Locked-box transactions may not use a closing working capital adjustment, but the buyer still needs to test whether the locked-box balance sheet contains normal working capital.
Establish the balance-sheet history before negotiating the peg.
Ask Veripoint for the latest available financial statements, multi-year working-capital movements, ownership context and the evidence gaps to request next.
Start a company analysisThis article is educational and does not provide investment, accounting, tax or legal advice. All transaction figures, charts and examples are illustrative and do not describe a real company.